Edinburgh Visitor Levy (Tourist Tax) Now in Force
Date Posted:
November 3, 2026
Share This:
Categories:
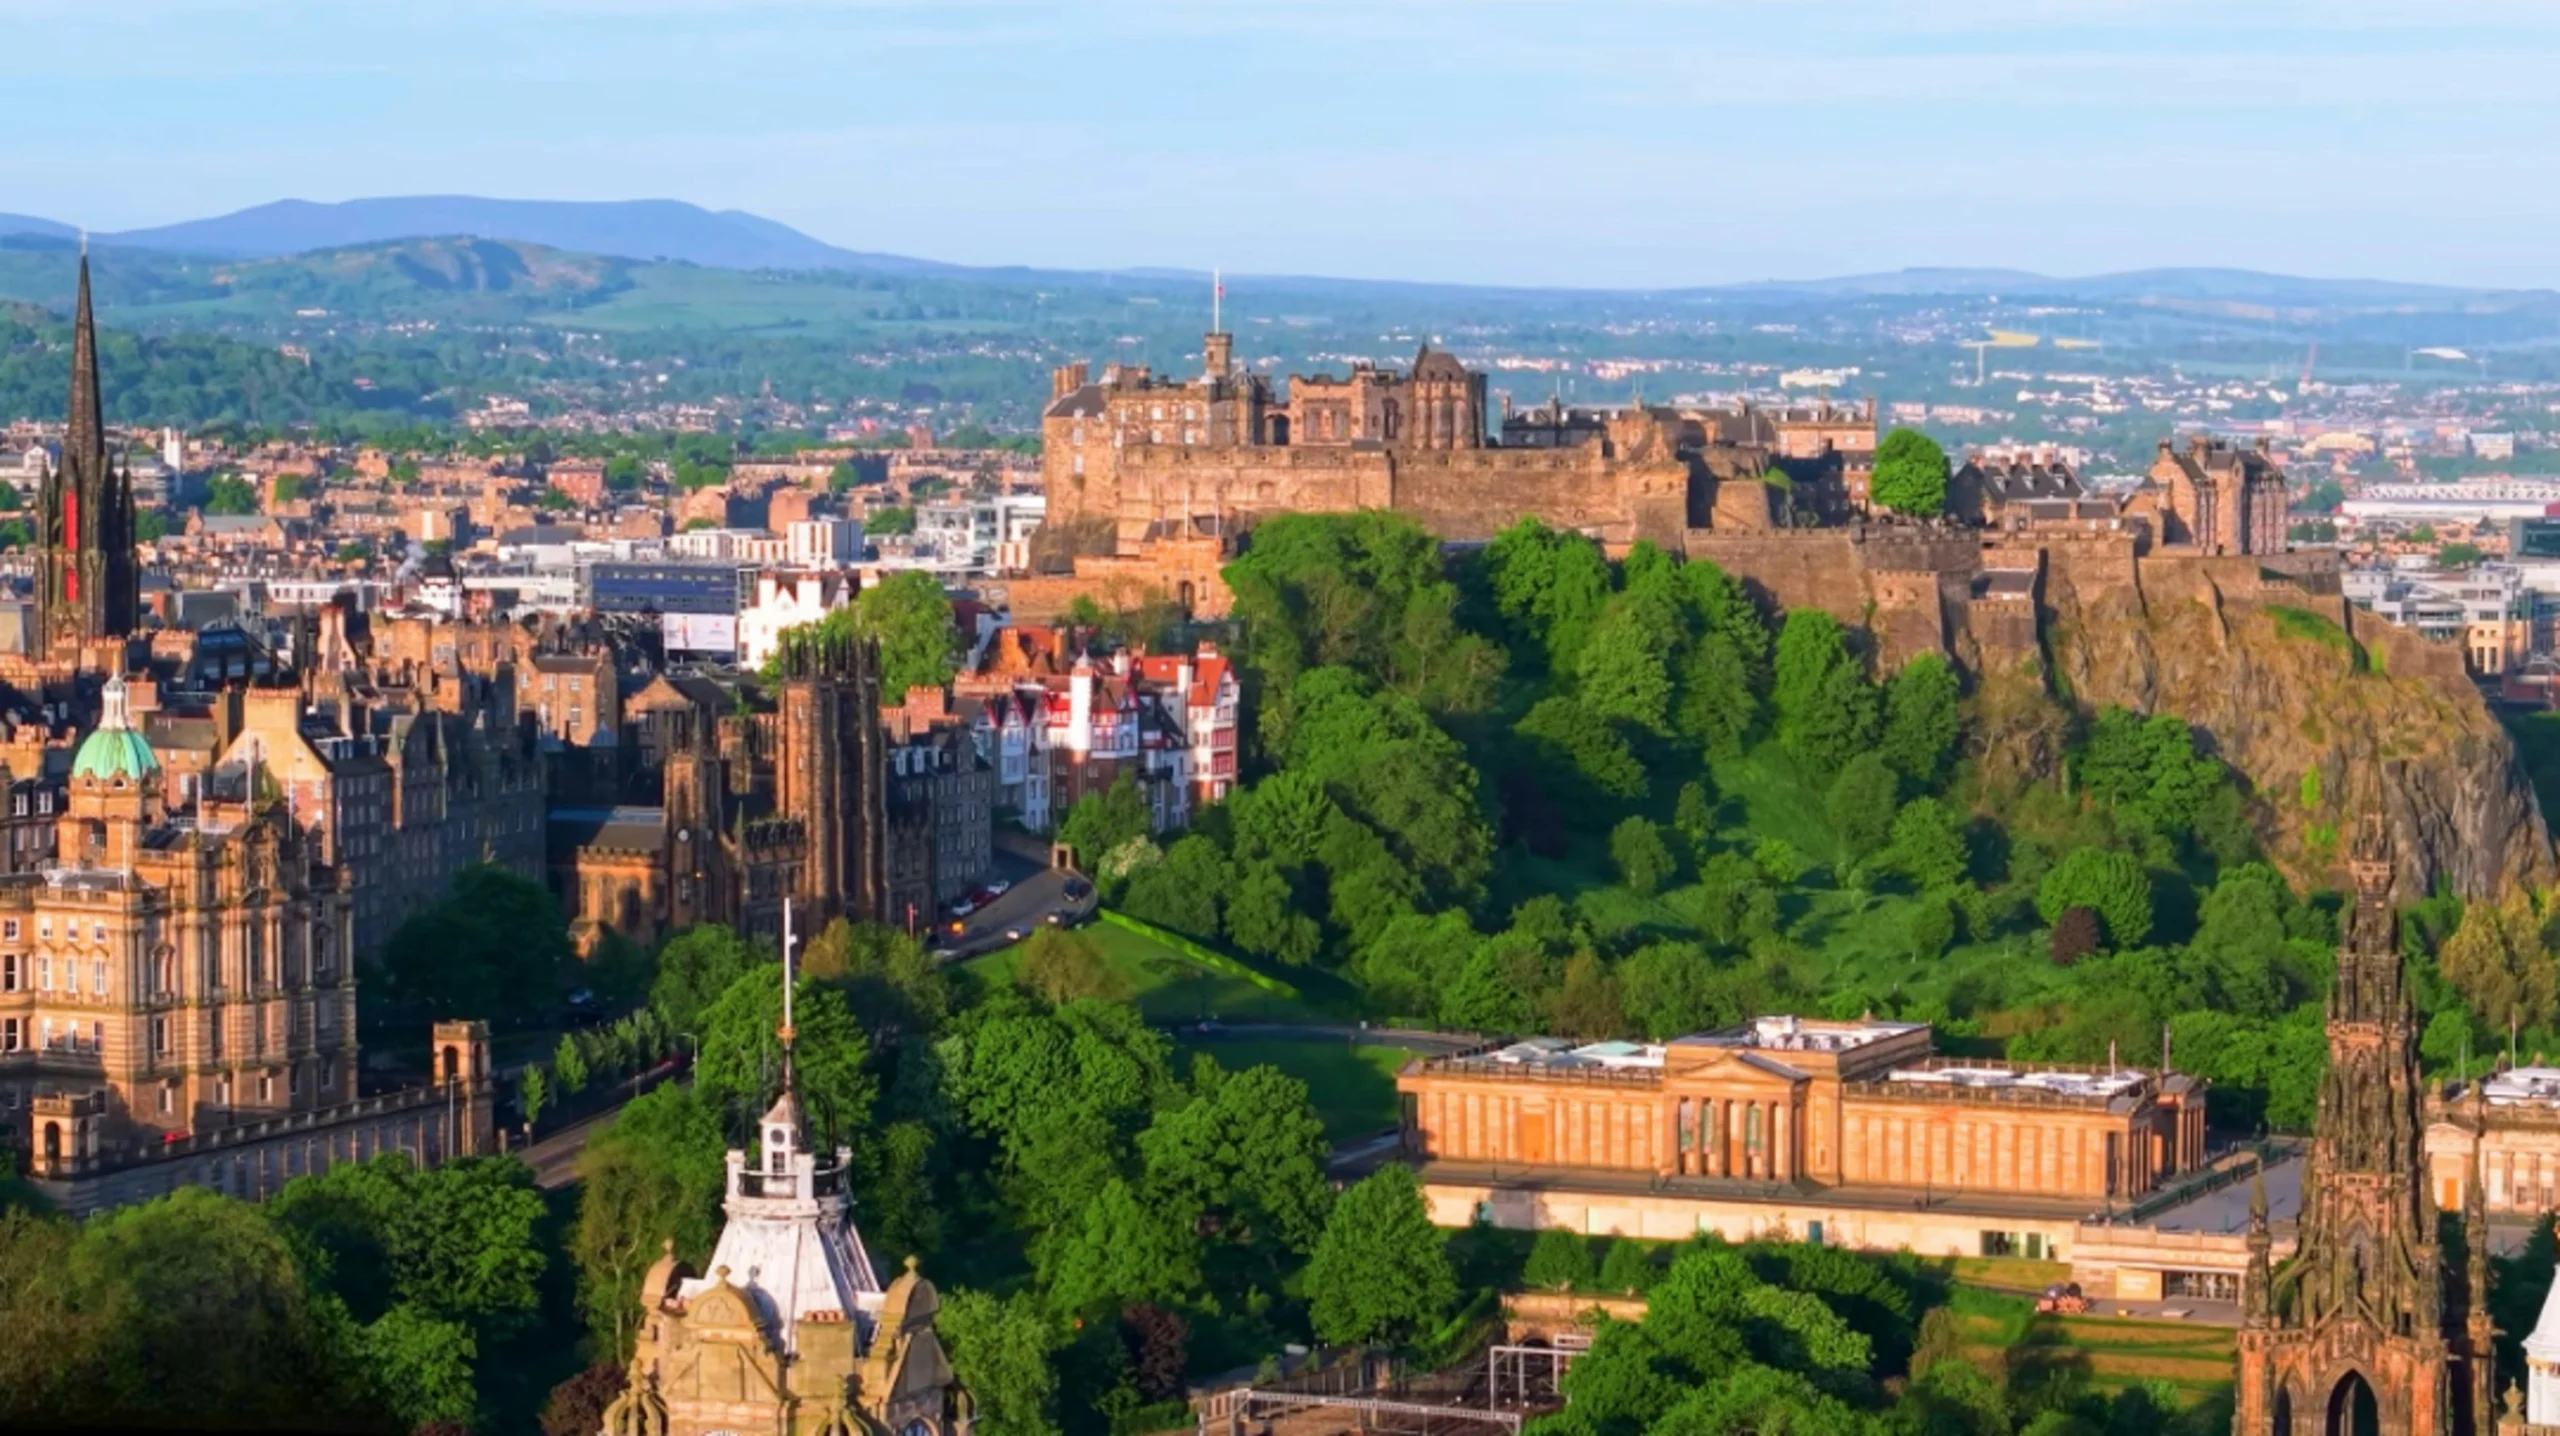
The City of Edinburgh is one of the world’s leading tourist destinations, attracting millions of visitors each year. From 24 July 2026, a 5% Visitor Levy (often referred to as a Tourist Tax) has been introduced for all short-term paid overnight accommodation within the city boundary.
While the levy has proved controversial in some quarters, it is projected to generate approximately £50 million annually for the council. These funds will be reinvested in local infrastructure, including affordable housing, public parks, cultural events, and tourism initiatives.
What does this mean for accommodation providers?
In short, the 5% levy must be applied to all paid overnight stays from 24 July 2026, provided the booking was made on or after 1 October 2025.
The levy applies to most forms of overnight accommodation, including:
- Hotels
- Bed and breakfasts
- Self-catering properties
- Hostels
- Campsites
- Caravan parks
The charge is applied to the accommodation cost only, excluding optional add-ons such as meals and parking. The levy is capped at a maximum of five consecutive nights.
Property owners are responsible for calculating and collecting the levy from guests and remitting it to the City of Edinburgh Council.
Your responsibilities
Accommodation providers must ensure they have robust systems in place to track and calculate levies accurately, while retaining appropriate supporting records.
This includes:
- Identifying stays longer than five nights and applying the levy only to the first five consecutive nights.
- Recording the net accommodation cost separately from optional extras.
- For businesses operating dynamic pricing models, calculating the charge based on the actual cost of each of the first five nights rather than using an average nightly rate for the entire stay.
Third-party booking platforms such as Airbnb and Booking.com will incorporate the levy into the overall booking cost and pass the funds to accommodation providers. However, the legal responsibility for tracking, reporting, and paying the levy to the council remains with the accommodation provider.
Providers must submit quarterly returns through the centralised platform, visitorlevy.scot. The first return was due by 30 October 2026 and covers the period from 24 July to 30 September 2026.
Payment must be made within 14 days of the return deadline.
To help offset administration costs, accommodation providers may retain 2% of the total levy collected.
Help available
A variety of software packages are available to bridge the gap between booking platforms such as Airbnb and Booking.com and the council’s reporting requirements. While these solutions can streamline the process, they can also be expensive and typically do not reconcile income with HMRC submissions such as VAT returns.
We can calculate and provide you all the necessary information for the returns, helping ensure compliance while reducing the administrative burden on your business.
Future developments
A 5% Visitor Levy will also be introduced within the Glasgow City boundary from 25 January 2027 for bookings made on or after 1 April 2026. Unlike the Edinburgh scheme, there is no cap on the number of chargeable nights.
Visitor levies are also scheduled to be introduced in:
- Aberdeen from April 2027 – 7% applying to the full stay
- Stirling from June 2027 – 3% applying to the full stay
- West Dunbartonshire from July 2027 – 5% applying to the full stay
Consultations are currently ongoing regarding the potential introduction of visitor levies in other Scottish local authority areas.